
Does Your Car Insurance Cover Modifications? (Rims, Body Kits, and Performance)
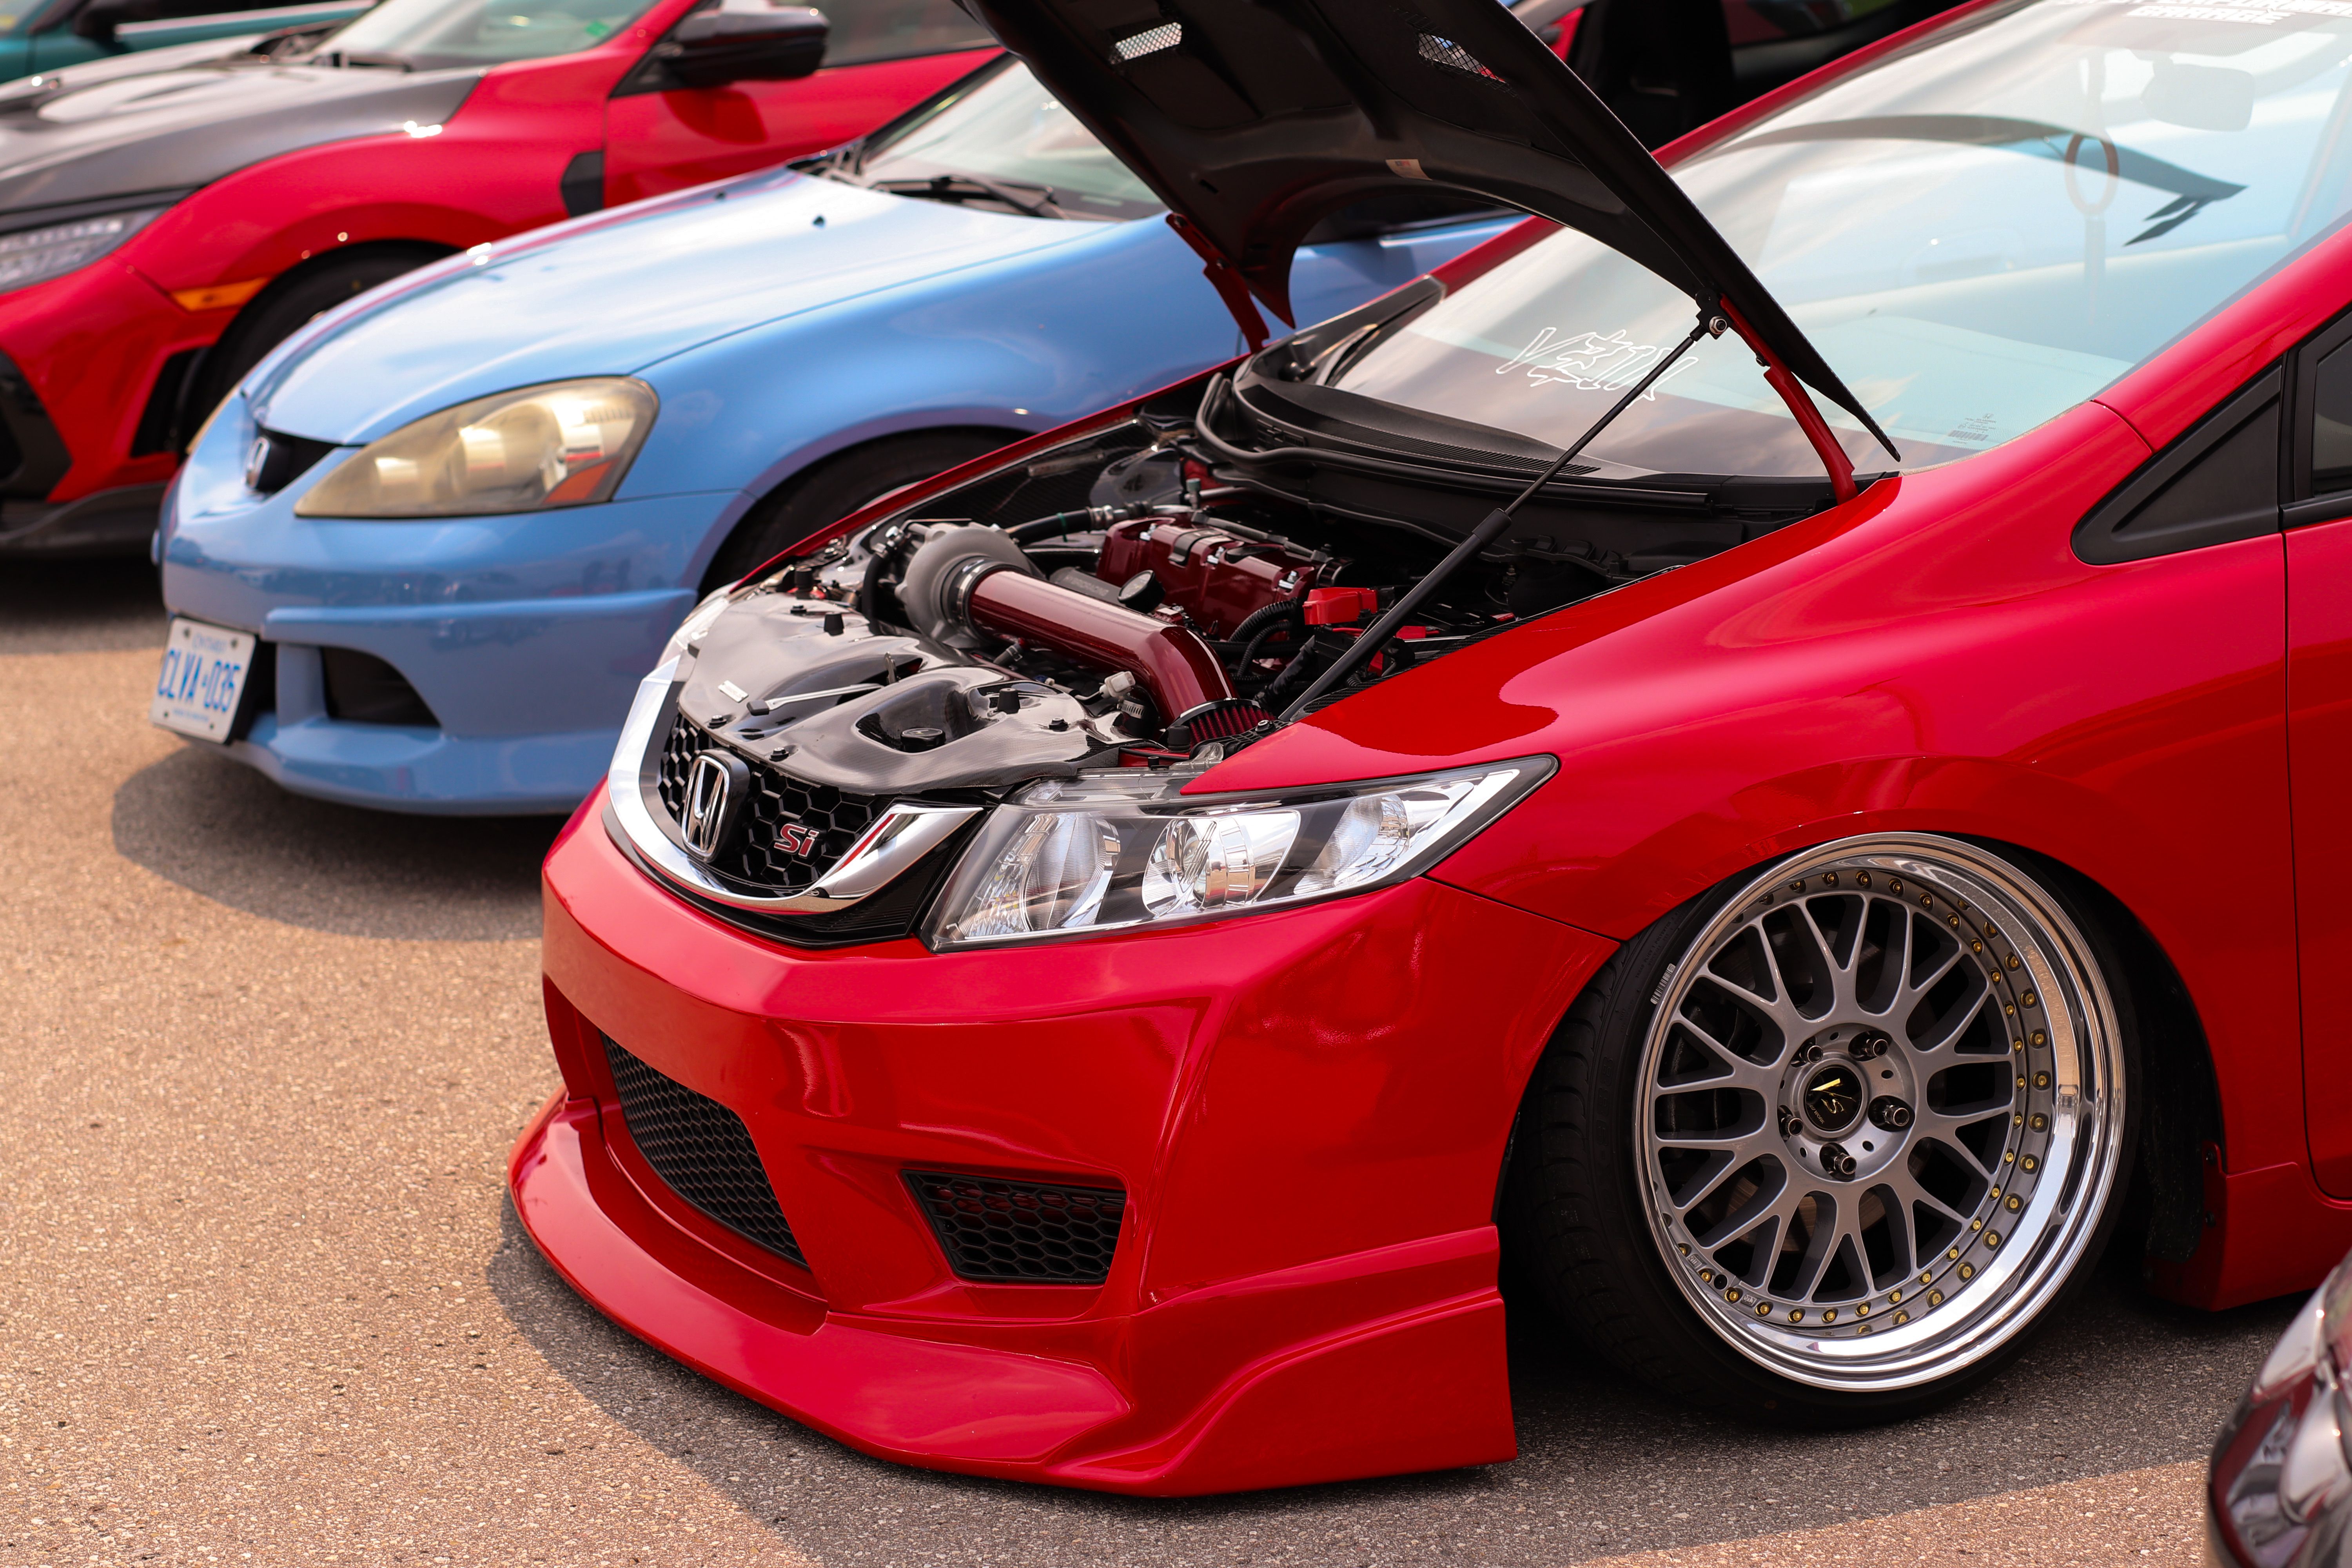
In the Malaysian automotive scene, "standard itu indah" (standard is beautiful) is a mantra rarely followed. Whether it's a set of aftermarket rims on a Myvi or a performance-tuned remap on a continental ride, modifications are part of our car culture.
But from an insurance perspective, once you modify your car without declaring it, your car is technically no longer the vehicle your insurer originally agreed to cover. This touches on the insurance principle of utmost good faith (Uberrimae Fidei) — you're expected to disclose anything that materially changes the risk the insurer is taking on.
The Legal Framework: JPJ and Your Policy
Under Section 12 of the Road Transport Act 1987, any modification made to a vehicle — before or after registration — must comply with JPJ's rules. So is a body kit legal in Malaysia? It depends on the dimensions.
According to JPJ's official vehicle modification guideline, spoilers, side skirts and aerofoils must not protrude more than 150mm, measured from the outer edge of the rear tyre. If your kit exceeds this, it could be flagged as an illegal modification — and that alone can complicate a claim if you're in an accident.
Many car owners also wonder if they need to declare sport rims to their insurer. The answer is yes. A rim upgrade might look purely cosmetic, but it changes your car's insured value (Sum Insured).
If your upgraded rims are stolen and were never declared, your insurer may only honour the value of factory-standard parts — or decline that part of the claim entirely, citing undisclosed material facts.
Why Non-Disclosure is a Risk You Can't Afford
When an adjuster assesses a claim, part of the job is checking that your car matches what's stated on the policy. If they find an undeclared turbocharger, a wide-body kit, or any other change that wasn't mentioned at renewal, they can raise a misrepresentation issue.
Depending on how serious it is, this can lead to your claim being rejected — or in more serious cases, your policy being voided — leaving you to cover repair costs or third-party liabilities yourself.

Renewing With PolicyStreet
PolicyStreet’s Drive+ Membership ensures you stay on top of your coverage without the headache. When you renew your car insurance through us, you gain access to our expert support to ensure every bolt-on is accounted for.
By purchasing Drive+, you not only can get up to RM120 road tax discount but also benefit from various partner vouchers. This allows you to reallocate your savings toward legitimate, declared upgrades.
Renew or compare your car insurance at PolicyStreet, where you can check coverage options for your modified ride before you need to make a claim. Compare car insurance with PolicyStreet.
Frequently Asked Questions
1. Will declaring my modifications significantly increase my insurance premium?
Not necessarily. Performance upgrades might lead to a slight premium increase due to added risk, but purely aesthetic modifications often have minimal impact. It's a small trade-off for a claim that won't be rejected over non-disclosure.
2. Can I claim for my modifications if I have a Comprehensive policy?
Only if those modifications are specifically listed as accessories in your policy schedule. A standard Comprehensive policy covers your car in its original factory state unless the modifications are declared and endorsed.
3. What happens if JPJ summons me for my rims? Does my insurance still work?
If your modifications are found to be illegal by JPJ, your insurer may decline a related claim — and in more serious cases, void the policy. Insurance is designed to cover legal risk, and an illegal modification can be treated as a breach of your policy's terms.
4. Is a "Stage 1 Remap" considered a modification I must declare?
Yes. Any change to your engine's performance parameters is a material fact. If there's an engine failure or accident and the insurer finds the ECU was tuned, they can use that as grounds to reject the claim.


